 (1).webp "When to Review Life Insurance")
Most of us buy a life insurance policy once, file the papers in a drawer and forget about it. The premium gets paid, the reminder comes every year, and life carries on. But your life doesn't stay the same, and a policy bought at 25 may not fit the person you are at 35 or 45.
A regular life insurance policy review is one of the simplest things you can do for your family's security. It doesn't take long, and it can catch gaps before they become real problems. Here are five life events that should make you pull that file out of the drawer.
Why a Review Matters
Think of your policy like a house key. It only works if it still fits the lock. Over time, several things change without you noticing:
-
Your income and expenses grow
-
Your family gets bigger
-
You take on loans and long-term commitments
-
Inflation quietly reduces what your cover can actually buy
-
The people you named as nominees may no longer be the right ones
A cover of ₹50 lakh may have felt generous ten years ago. Today, with rising school fees, medical costs and living expenses, the same amount may not go nearly as far. That's why timing your review around big life changes works better than waiting for a random reminder.
1. Getting Married
Marriage is often the first moment your financial decisions affect another person. Even if your spouse works, a shared home, shared plans and shared expenses mean the loss of one income would be felt by both.
At this stage, it helps to check:
-
Whether your cover is enough to support your spouse and protect shared goals
-
Whether your nominee should be updated to your spouse
-
Whether your spouse also needs their own cover
If you're young and healthy, this is also a good time to consider a term plan. Premiums are generally lower when you buy earlier, and a pure protection plan can give you a large cover at an affordable cost.
2. Having a Child
A new baby brings joy, and a long list of future costs: education, healthcare, and years of daily expenses. Your responsibilities grow the day your child is born, and your insurance should grow with them.
Ask yourself how many years your child will depend on you, and what it would take to fund their studies and everyday needs if you weren't around. Then check:
-
Whether your current cover reflects these longer-term needs
-
Whether you should add a top-up cover or a separate plan
-
Whether your nominee details and, if relevant, your will name someone to look after your child
Many advisors suggest that cover should be a multiple of your annual income, often 10 to 15 times, though the right figure depends on your loans, family size and goals.
3. Buying a Home or Taking a Big Loan
A home loan is usually the biggest financial commitment most families make, and it can run for 15 to 25 years. If something happens to the earning member, the EMIs don't stop. The family may be left with a loan and a shrinking income.
Here's an example. Suppose a couple in a South Gujarat town buys a flat with a 20-year home loan, but the husband's life cover hasn't changed since before the purchase. If he passes away in year five, his family is left to handle the EMIs on top of daily expenses.
Before or soon after taking a loan, review whether your cover is enough to clear the outstanding amount and still support your family. Reviewing your overall life insurance ensures the cover matches the size and length of your liabilities.
4. A Big Change in Income, Job or Business
A promotion, a job switch, a new business or a sharp rise in income all change your lifestyle, and with it, what your family would need. The reverse matters too. If your income has dropped, you may need to check that you can comfortably keep paying your premiums.
Here is what to check:
-
Whether your cover has kept pace with your income
-
Whether your premiums are still affordable
-
Whether you need extra protection for business loans or partners
-
Whether your employer's group cover (if any) is being mistaken for a full solution, since it usually ends when you leave the job
If you've just started a business, this is especially important. Your earnings may be less predictable, but your responsibilities are often higher.
5. Nearing Retirement or Facing a Major Health or Family Change
As you approach retirement, your needs shift from protecting your income to protecting your savings and your spouse's future. Your children may be independent, your loans may be nearly paid off, and your priority may become a steady income after work.
This is a good time to look at retirement planning alongside your insurance, so your savings, policy maturities and monthly income all work together.
The same review is worth doing after other big changes, such as:
-
A serious illness in the family
-
The death of a parent or spouse
-
A divorce or separation
-
A child becoming financially independent
Your health insurance deserves a look at this stage as well. Medical costs tend to rise with age, and a strong life cover is of little use if a single hospital bill drains your savings.
A Simple Policy Review Checklist
When any of these events happen, run through this quick list:
-
Cover amount: is it enough for your loans, family needs and future goals?
-
Nominee: is the name current, with correct details?
-
Policy term: does it last until your responsibilities end?
-
Riders: do you need add-ons like critical illness or accidental death cover?
-
Premium: is it affordable for the long run?
-
Policy documents: can your family easily find them?
Common Mistakes to Avoid
-
Assuming an old policy is still enough
-
Forgetting to update the nominee after marriage or a birth
-
Relying only on employer cover
-
Cancelling or letting a policy lapse without checking alternatives
-
Buying a new policy without reading the terms and exclusions
-
Never reviewing at all
Final Thoughts
You don't need to review your policy every month. You just need to remember that life's big moments are also financial moments. Marriage, a child, a home loan, a career change and retirement each change what your family needs, and your insurance should keep up.
Policy terms, tax treatment and benefits vary by plan and by current rules, so always read the policy documents carefully. If you'd like help checking whether your cover still matches your life, talk to our advisors at Shah Finserv.
Latest Blog
-
September 25, 2026
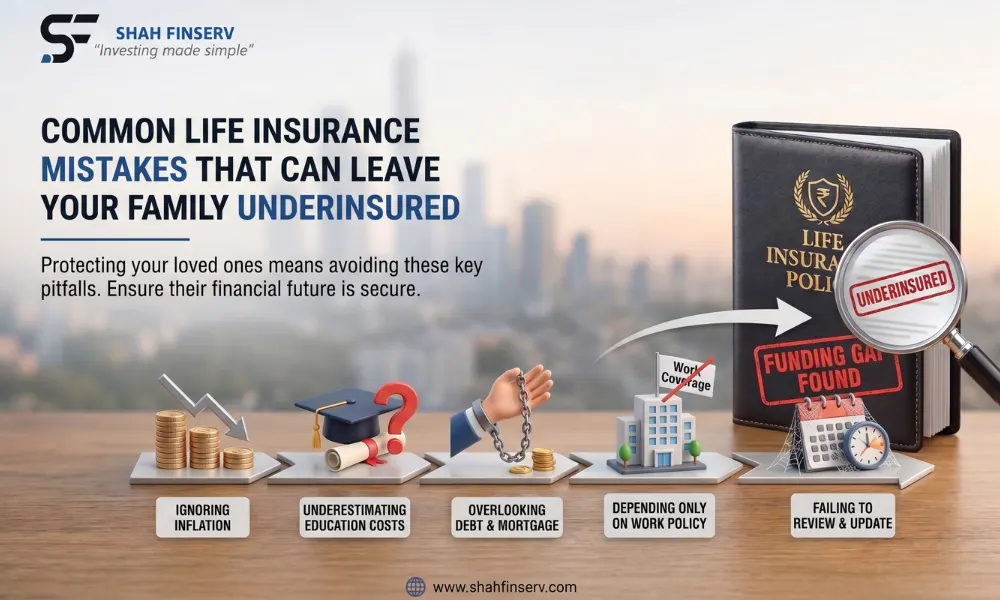
Common Life Insurance Mistakes That Can Leave Your Family Underinsured
We Deals In