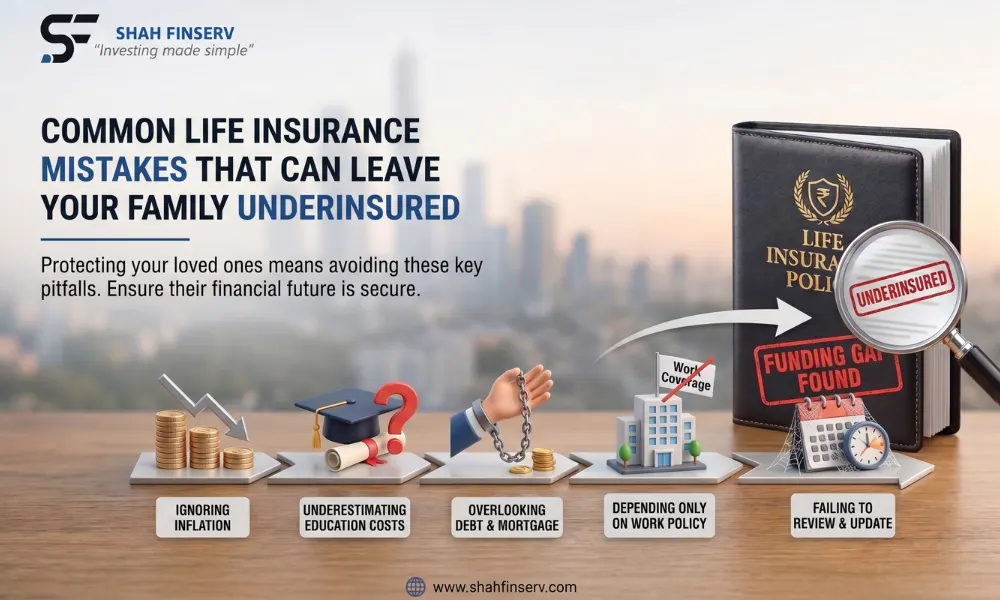
Most people feel relieved once they've bought a life insurance policy. The premium is paid, the papers are filed, and the box is ticked. But having a policy and having enough protection are two different things, and the gap between them usually stays invisible until the day the family actually needs the money.
By then, it's too late to fix. The good news is that most cases of underinsurance come from a handful of common, avoidable mistakes. Let's look at them, and at how to steer clear.
What Does Underinsured Really Mean?
You're underinsured when your cover wouldn't be enough to keep your family's life on track if you were gone. That means paying off loans, running the household, funding children's education and covering long-term goals, not just meeting the next few months of expenses.
A simple test: if your income stopped tomorrow, how many years could your family maintain their lifestyle on the payout? If the honest answer is "not many," there's a gap worth closing.
Mistake 1: Buying Too Little Cover
This is the most common one. People often choose a cover amount because the premium looks comfortable, not because the number matches their responsibilities. A sum that sounded large when you bought it may be modest against today's school fees, medical costs and living expenses.
Many advisors suggest a cover of around 10 to 15 times your annual income, adjusted for your loans, family size and goals. Treat that as a starting point, not a rule.
Mistake 2: Buying Insurance Only to Save Tax
Tax benefits are a welcome bonus, but they shouldn't be the reason you buy. When tax saving drives the decision, people often end up with a low cover amount and a policy that doesn't match their real needs. Tax treatment also depends on the policy and on current rules, so it can change.
Start with the question "how much protection does my family need?" and let tax benefits come second.
Mistake 3: Mixing Insurance and Investment
Some plans combine life cover with savings, and they suit certain goals. The mistake is expecting one product to do both jobs well. Savings-linked plans usually offer a lower cover for a higher premium, which can leave you underprotected.
Many families prefer to keep the two apart:
-
A pure term plan for a large, affordable cover
-
Separate investments for wealth creation
The right mix depends on your situation, so compare before you commit.
Mistake 4: Relying Only on Employer Cover
Group insurance from your employer is a nice perk, but it's rarely enough on its own. The cover is often modest, and it usually ends when you leave the job, sometimes at exactly the stage when getting new cover gets harder or more expensive.
Think of employer cover as a bonus layer, and keep your own policy as the foundation.
Mistake 5: Waiting Too Long to Buy
"I'll do it later" is expensive. Premiums generally rise with age, and health conditions that appear over time can make cover costlier or harder to get. Buying early locks in a lower premium for the whole term.
Take a young professional in Vapi who delays insurance because "there's plenty of time." Five years and a health scare later, the same cover costs noticeably more. Nothing dramatic happened, the delay itself did the damage.
Mistake 6: Not Disclosing Details Honestly
This one can hurt the most. When you apply, the insurer asks about your health, habits like smoking or drinking, occupation and income. Hiding or understating these details may look like a way to get a cheaper premium, but incorrect information can lead to a claim being questioned or rejected later.
Be complete and truthful on the proposal form. It protects your family's claim when it matters most.
Mistake 7: Forgetting to Update Nominees and Review the Policy
Life moves on, but policy details often don't. A nominee named years ago may no longer be the right person after marriage, a child's birth or a family loss. And a cover chosen at 27 may not fit you at 40.
A quick review every couple of years, and after big life events, keeps your policy aligned with your life. Also make sure your family knows the policy exists and where the documents are kept.
Mistake 8: Ignoring Health Cover and Riders
A strong life cover can still be undermined by a single major hospital bill. If medical costs drain your savings, your family's long-term security suffers even while you're alive. Good health insurance works alongside life cover, not instead of it.
Optional riders, such as critical illness or accidental death benefit, can add another layer. They cost extra, so choose based on your real risks rather than adding everything.
Mistake 9: Buying Without a Goal
Insurance works best when it's linked to what you actually want to protect: a home loan, children's education, a spouse's income, a family business. Without clear goals, it's hard to know what number is enough. Structured goal-based planning helps you connect each responsibility to the right amount of cover.
A Quick Self-Check
Ask yourself:
-
Would my cover repay all my loans and still support my family for years?
-
Is my cover roughly in line with my income and goals?
-
Have I relied mainly on tax saving or on employer cover?
-
Is my nominee current?
-
Did I disclose everything accurately?
-
Do I have adequate health cover?
If you answered "no" or "not sure" to any of these, your family may have a gap.
Final Thoughts
Being underinsured rarely feels like a problem while everyone is healthy and life is running smoothly. That's exactly why it's so easy to miss. A few honest questions, a clear picture of your responsibilities and a regular review can make the difference between a policy that exists and a policy that actually protects.
Terms, benefits and tax treatment vary by plan and by current rules, so read your policy documents carefully. If you'd like help checking whether your family's cover is truly enough, talk to our advisors at Shah Finserv. You can also read more about life insurance options to compare plans and cover types.
Latest Blog
-
September 18, 2026
 (1).webp "Review Life Insurance Policy")
5 Life Events That Should Make You Review Your Life Insurance Policy
-
September 11, 2026
Succession Planning for Family-Owned Businesses in Gujarat
We Deals In