Most investors spend their time asking which mutual fund to buy. A more useful question comes first: how much of your money should go into equity, how much into debt, and how much into gold or cash? The answer is your asset allocation strategy, and it shapes how your portfolio behaves in good markets and bad ones far more than any single fund choice.
This guide explains what asset allocation is, how to decide your own mix, and how mutual funds make it easy to put into practice.
What Is Asset Allocation?
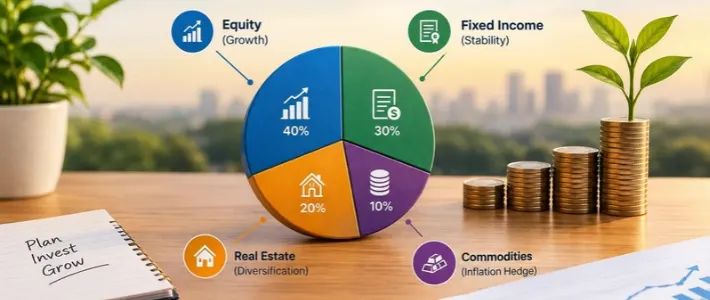
Asset allocation means dividing your investments across different asset classes so that no single market movement can derail your goals. Each asset class behaves differently:
-
Equity (shares and equity mutual funds) offers the highest long-term growth potential, but with sharp ups and downs along the way.
-
Debt (debt mutual funds, bonds, fixed income) is steadier and adds stability, though returns are usually lower over long periods.
-
Gold often moves independently of equity and can cushion a portfolio during uncertain times.
-
Cash and liquid funds keep money available for emergencies and near-term needs.
Because these assets rarely move in the same direction at the same time, combining them smooths the journey. When one part of the portfolio falls, another may hold steady or rise.
Why Asset Allocation Matters More Than Fund Picking
Two investors can buy good funds and still have very different experiences. One holds 90% equity and panics when the market falls 25%. The other holds a balanced mix, stays calm and keeps investing. The second investor often ends up better off, not because of smarter fund selection, but because the allocation matched their ability to stay invested.
A sound allocation helps you to:
-
Control risk so that a bad year does not undo years of progress
-
Stay disciplined instead of reacting to headlines
-
Match investments to goals and timelines
-
Avoid depending on one asset class to get lucky
How to Decide Your Asset Allocation Strategy
There is no single correct mix. Your allocation should reflect four things.
1. Your goals and time horizon. Money needed in two years should not sit in equity. Money you will not touch for fifteen years can handle more market swings. A goal like kids education planning, due in a fixed number of years, usually needs a gradual shift from equity to safer assets as the date approaches.
2. Your risk tolerance. This is how you feel when your portfolio drops. If a 20% fall would make you sell, a heavy equity allocation is not right for you, whatever the textbooks say.
3. Your risk capacity. This is how much loss you can actually afford. A salaried person with a stable income and no major liabilities can usually take more risk than someone supporting a family on irregular income.
4. Your stage of life. Younger investors typically hold more equity because they have time to recover from downturns. Those nearing or in retirement usually move toward debt and income-focused assets to protect what they have built.
Business owners deserve a special mention. If your income already depends on the economy, for example in an industrial region like Vapi and the wider South Gujarat belt, keeping part of your personal wealth in steadier assets provides a useful counterweight to business risk.
Sample Asset Allocation Mixes
The table below shows illustrative ranges only. It is not a recommendation, and the right mix for you depends on your own situation.
|
Investor profile |
Equity |
Debt |
Gold / others |
|
Aggressive (long horizon, high risk comfort) |
70-80% |
10-20% |
5-10% |
|
Moderate (balanced approach) |
50-60% |
30-40% |
5-10% |
|
Conservative (short horizon, low risk comfort) |
20-30% |
60-70% |
5-10% |
A useful starting point many people use is to subtract their age from 100 and treat the result as a rough equity share, then adjust for personal circumstances. It is a rule of thumb, not a rule.
Building Your Allocation With Mutual Funds
Mutual funds are one of the simplest ways to follow an asset allocation strategy, because each category already gives you diversified exposure:
-
Equity funds: large-cap and flexi-cap funds for core growth. Mid-cap and small-cap funds can add growth potential but swing more, so they usually suit a smaller slice of a long-term portfolio.
-
Debt funds: for stability and predictable income, matched to how long you can stay invested.
-
Hybrid funds: these combine equity and debt in one fund, useful if you want a ready-made balance.
-
Gold funds: a convenient way to hold gold without storing it physically.
-
Liquid funds: for emergency money and short-term needs.
Through a monthly SIP, you can build each part of the allocation gradually without worrying about market timing. If you are unsure whether to invest gradually or all at once, our guide on SIP vs lump sum investment explains the trade-offs. You may also want to read Gold vs Mutual Funds to see how gold fits alongside your equity holdings.
Rebalancing: Keeping Your Strategy on Track
Over time, markets change your allocation without you doing anything. If equity has a strong year, a 60:40 portfolio may drift to 70:30, which means you are taking more risk than you planned.
Rebalancing brings the portfolio back to its target mix. Two common approaches are:
-
Time-based: review once a year and adjust.
-
Threshold-based: rebalance whenever any asset class drifts more than about 5 percentage points from its target.
You can also rebalance by directing new SIP money towards the under-weight asset, which avoids selling anything. Selling units can trigger capital gains tax, so check the tax impact before making changes. Rebalancing is also a calm, rule-based response during uncertain periods, as covered in our article on investment planning during market volatility.
Common Asset Allocation Mistakes to Avoid
-
Chasing last year's best performer. Past returns do not guarantee future results.
-
Over-concentrating in one asset class, one sector, or one fund category.
-
Never reviewing. A mix that suited you at 30 may not suit you at 45.
-
Ignoring emergency funds and being forced to sell investments at a bad time.
-
Copying someone else's portfolio without checking whether their goals and risk capacity match yours.
Build a Mix That Fits Your Goals
Asset allocation works best when it is tied to your real goals rather than a generic formula. At Shah Finserv, we help families and business owners across Vapi, Valsad and nearby areas build mutual fund portfolios around their goals, risk comfort and timelines. Explore our mutual fund services, or contact us to plan an allocation that suits you.
Related Blogs

We Deals In
Frequently Asked Questions
There is no single best strategy. The right one depends on your goals, time horizon, risk tolerance and income stability. A good strategy is one you can follow consistently through market ups and downs.
At least once a year, and also after major life events such as marriage, a new child, a change in income or approaching retirement.
Yes. You can split your SIP across equity, debt and gold funds, or choose a hybrid fund that holds a mix of assets within a single scheme.
Usually, yes. Most people shift towards debt and income-generating investments to protect capital, while keeping some equity to help savings keep pace with inflation over a long retirement.
Not exactly. Asset allocation decides how much of your money goes into each asset class, such as equity, debt and gold. Diversification then spreads each part across different funds, sectors and companies. Allocation comes first, and diversification happens within each class.