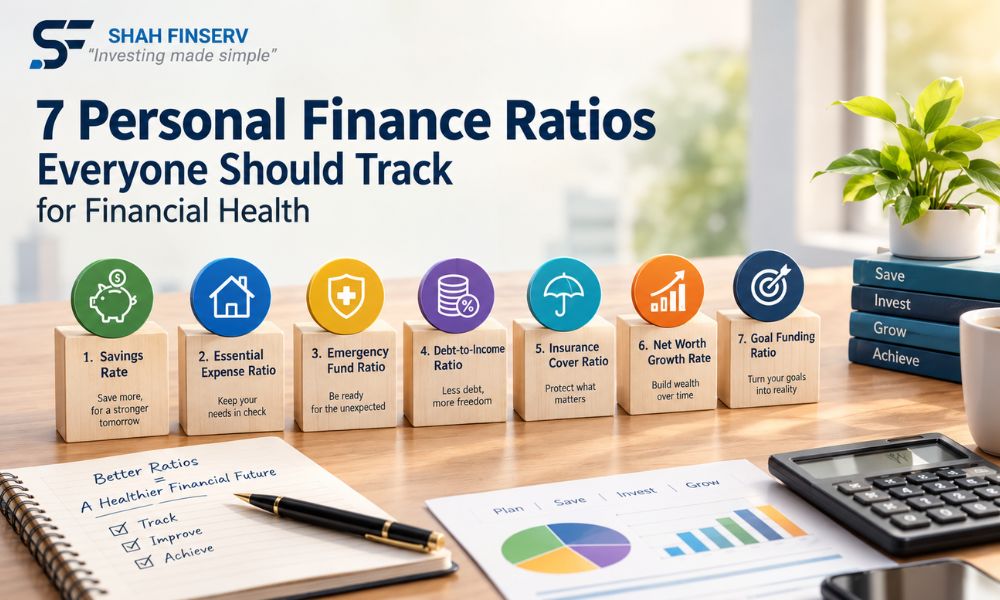
Most people check their bank balance regularly, yet very few know whether their finances are actually healthy. A large balance can hide too much debt, too little insurance or savings that are not growing. Personal finance ratios solve this by turning your money into a few simple numbers you can measure and improve.
This guide explains seven personal finance ratios, how to calculate each one, and what a healthy range looks like. None of them needs special software, only your income, expenses and a calculator.
Why Personal Finance Ratios Matter
A ratio compares one part of your finances to another, for example your savings to your income. This makes your situation easy to judge, whatever your income level. Tracking them once or twice a year helps you spot problems early, see whether you are improving, and decide where to focus next.
The benchmarks below are general rules of thumb, not strict rules. Your own targets depend on your goals, age, family situation and income stability.
1. Savings Rate
Formula: Monthly savings ÷ monthly gross income × 100
Your savings rate shows how much of your income you actually keep and put to work. If you earn ₹1,00,000 and save ₹20,000 a month, your savings rate is 20%.
Healthy range: Many planners suggest saving at least 20% of income, and more if you start late or have big goals ahead.
How to improve it: Automate savings on salary day, and raise your SIP or savings amount whenever your income increases.
2. Essential Expense Ratio
Formula: Essential monthly expenses ÷ monthly gross income × 100
Essential expenses include rent or EMI, groceries, utilities, school fees, transport and insurance premiums. If these cost ₹50,000 on an income of ₹1,00,000, the ratio is 50%.
Healthy range: Around 50% or less is a common guide, following the popular 50-30-20 approach of needs, wants and savings.
How to improve it: Review recurring costs once a year. Small cuts in subscriptions, utility use or unused services add up.
3. Emergency Fund Ratio
Formula: Liquid savings ÷ monthly expenses
This tells you how many months you could manage without income. If you have ₹3,00,000 in easily accessible savings and spend ₹60,000 a month, you have 5 months of cover.
Healthy range: Three to six months of expenses is the usual guide. Business owners and people with irregular income often keep more.
How to improve it: Build it gradually, with a fixed monthly amount until you reach your target. Our guide on emergency fund planning explains how much to keep aside.
4. Debt-to-Income Ratio
Formula: Total monthly loan payments ÷ monthly gross income × 100
This ratio shows how much of your income goes to EMIs and other debt payments. If you pay ₹25,000 in EMIs on an income of ₹1,00,000, the ratio is 25%.
Healthy range: Many advisors suggest keeping it below roughly 35% to 40%. A lower number gives you more room to save and handle surprises, and lenders also look at this when you apply for a loan.
How to improve it: Clear high-interest loans first, avoid taking new debt unnecessarily, and think carefully before a large purchase. If you are planning a house purchase, read financial planning before applying for a home loan.
5. Insurance Cover Ratio
Formula: Total life cover ÷ annual income
This checks whether your family could maintain its lifestyle if your income stopped. With an annual income of ₹12,00,000 and a life cover of ₹1.2 crore, the ratio is 10 times income.
Healthy range: A common rule of thumb is a life cover of 10 to 15 times your annual income, adjusted for your loans, dependants and goals. Health cover should also be reviewed separately against medical costs in your city.
How to improve it: Review your cover after major life events such as marriage, a child or a new loan. Our article on life events that should make you review your life insurance policy covers the key moments.
6. Net Worth Growth Rate
Formula: (This year's net worth − last year's net worth) ÷ last year's net worth × 100
Net worth is everything you own minus everything you owe. If it rises from ₹10 lakh to ₹12 lakh in a year, your net worth growth rate is 20%.
Healthy range: There is no fixed number, but it should be positive and, over time, ahead of inflation. A falling net worth is a warning sign that spending or debt is outpacing your savings.
How to improve it: Increase your savings rate, pay down debt, and keep investments aligned with your time horizon.
7. Goal Funding Ratio
Formula: Amount saved for a goal ÷ amount you should have saved by now × 100
This is the ratio that connects your numbers to your life. Suppose you need to have ₹5 lakh set aside by now for your child's education and you have ₹4 lakh. Your goal funding ratio is 80%.
Healthy range: 100% or more means you are on track. Below that, you can increase your monthly investment or extend the timeline.
How to improve it: Give every goal an amount, a deadline and a monthly contribution. Our guide on child education planning shows how this works for one common goal.
Your Ratios at a Glance
The figures below use an illustrative household earning ₹1,00,000 a month.
|
Ratio |
Example result |
General benchmark |
|
Savings rate |
20% |
20% or more |
|
Essential expense ratio |
50% |
About 50% or less |
|
Emergency fund ratio |
5 months |
3 to 6 months |
|
Debt-to-income ratio |
25% |
Below about 35% to 40% |
|
Insurance cover ratio |
10 times income |
About 10 to 15 times |
|
Net worth growth rate |
20% |
Positive and ahead of inflation |
|
Goal funding ratio |
80% |
100% or more |
How to Use These Ratios
-
Calculate all seven once. Use your last three months of income and expenses for a realistic picture.
-
Find your weakest ratio. Fix that first, since it is usually the one putting your plan at most risk.
-
Set one clear target for each. For example, raise your savings rate from 12% to 15% this year.
-
Review every six to twelve months. Also review after major events such as a job change, a new loan or a new child.
-
Link the numbers to goals. Ratios are most useful when each rupee has a purpose, such as retirement, education or a home.
Common Mistakes to Avoid
-
Tracking only your bank balance, which says nothing about debt, insurance or goals.
-
Copying someone else's benchmarks without adjusting for your own situation.
-
Calculating once and never again. Your finances change, so your numbers should be reviewed.
-
Ignoring insurance and debt ratios because they feel unpleasant to look at.
-
Using ratios without goals, so there is no clear reason to improve them.
Turn Your Numbers Into a Plan
Ratios show where you stand, and goal-based planning shows where you want to go. At Shah Finserv, we help families and business owners across Vapi, Valsad and nearby areas link their savings and investments to real goals such as education, a home and retirement. Explore our goal-based planning services, or contact us to build a plan that fits your life.
Related Blogs
-
October 16, 2026
Creating Multiple Income Streams for Long-Term Financial Security
-
September 18, 2026
 (1).webp "Review Life Insurance Policy")
5 Life Events That Should Make You Review Your Life Insurance Policy
-
August 20, 2026

Financial Planning Before Applying for a Home Loan
We Deals In
Frequently Asked Questions
Personal finance ratios are simple calculations that compare parts of your finances, such as savings to income or debt to income. They help you judge your financial health quickly and track progress over time.
Personal finance ratios are simple calculations that compare parts of your finances, such as savings to income or debt to income. They help you judge your financial health quickly and track progress over time.
There is no single answer, since each one shows a different part of your finances. For most people, the savings rate, emergency fund ratio and debt-to-income ratio are the best place to start.
Once or twice a year is enough for most people, and also after major life events such as a job change, marriage, a new child or a new loan.
Once or twice a year is enough for most people, and also after major life events such as a job change, marriage, a new child or a new loan.
Many advisors suggest keeping total monthly debt payments below about 35% to 40% of gross income. A lower ratio gives you more flexibility, and the right level depends on your income stability and goals.
Yes. Reducing unnecessary expenses, clearing expensive debt and automating savings can improve several ratios at once, even if your income stays the same.